Infinite Banking in Canada: The Two Values of Your Policy Working at the Same Time
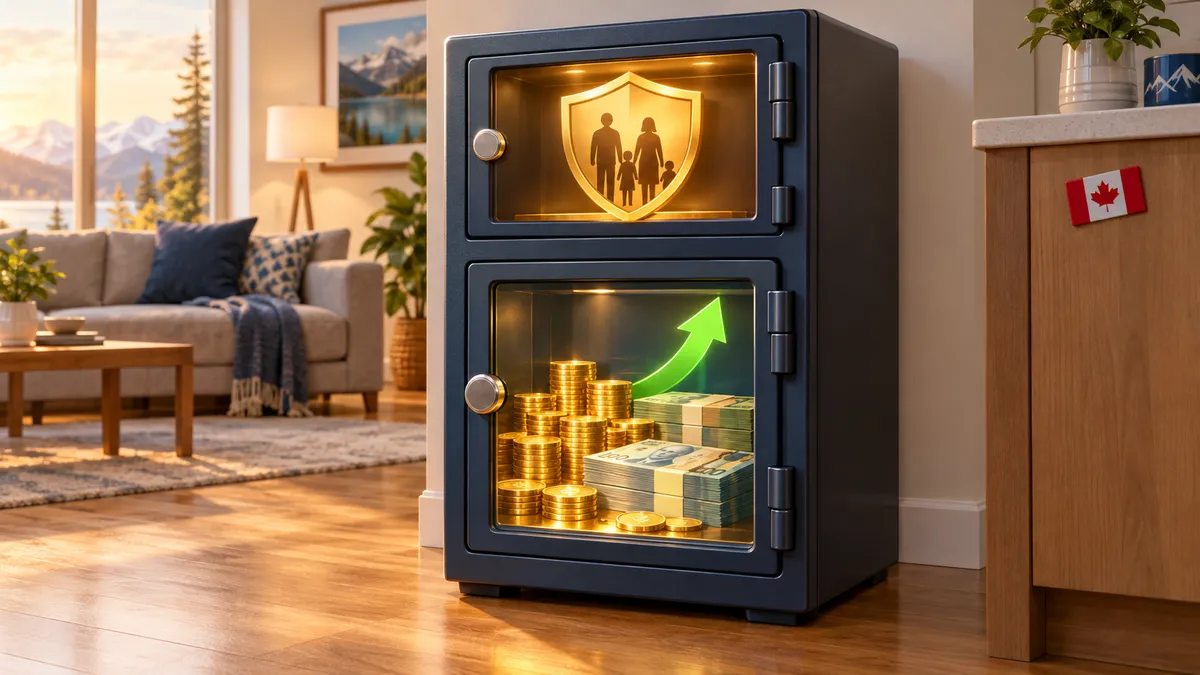
Imagine you have a stainless steel safe in your home.
Inside that safe, two wonderful things happen at the same time.
In the front section there is a quick-access compartment. You can open that door today and take out money for whatever you need: a business opportunity, a vehicle down payment, a family emergency, or simply to grow your capital in another way.
In the upper section there is a sealed deposit, larger. That deposit holds a treasure reserved exclusively to protect your family the day you are no longer here. That money is not touched during your lifetime. It waits, grows, and reaches your loved ones when they need it most.
A participating whole life policy, well designed for the Personal Banking System in Canada, works exactly like that. It has two values working for you at the same time from day one.
Value 1: The Cash Value
The cash value is the real, available money you accumulate inside your policy while you are alive.
It is not a number on paper. It is not a future promise. It is working capital you can use today to take loans, make investments, solve emergencies, or supplement your cash flow without touching your RRSP or depending on a bank.
When your policy is correctly structured with a Canadian mutual life insurance company, almost every dollar you contribute quickly converts into available cash value. That money grows year after year with two engines: the contractually guaranteed interest and the participating dividends you receive as a co-owner of the company.
What You Can Do with Your Cash Value Today
- Take a loan using your cash value as collateral, without a credit check and without interrupting the policy's growth.
- Use that money to buy a vehicle, fund a business, or cover an opportunity without asking anyone's permission.
- Supplement your cash flow during periods of variable income without liquidating other investments.
- Build an emergency fund that grows on its own, without market risk.
And while you use that money outside, your policy keeps growing inside on the full balance. Your money works in two places at the same time.
Value 2: The Death Benefit
The death benefit is the guaranteed amount that the Canadian mutual life insurance company will pay directly to your designated beneficiaries when you pass away.
This money arrives income-tax-free. It does not go through the probate process. It does not wait months or years in legal proceedings. It goes directly to the people you chose, within days, without government or court intervention.
That matters because in Canada, the probate process can be slow, public, and costly. The CRA (Canada Revenue Agency) treats all assets of a deceased person as if they had been sold on the day of death, which can generate significant taxes on capital gains, undrawn RRSPs, and other assets.
The death benefit of a participating whole life policy bypasses all of that process. It arrives clean, fast, and income-tax-free directly to those you love most.
A Feature Most People Do Not Know
As you contribute money to your policy and your cash value grows, your death benefit also grows. It is not a fixed amount that stays the same for decades. Each year your system is better capitalized, the larger the legacy you leave for your family.
The death benefit is not just the cherry on top. It is the part of the strategy that guarantees the work of your entire life does not dissolve in taxes and red tape when you are gone.
Both Values Work Together, Not Separately
Here is the concept that few advisors explain clearly in Canada.
Most people believe life insurance is for when you die. Period.
What makes a well-designed participating whole life policy unique is that the main emphasis is on growing the cash value and accessing that capital while you are alive. The death benefit exists and grows, but it is the complement to an active financial strategy, not the only purpose of the contract.
You are building a Personal Banking System that:
- Gives you liquidity and control today.
- Protects your family tomorrow.
- Grows in a guaranteed way every year.
- Transfers wealth to the next generation income-tax-free.
- All with the same dollar working in multiple directions at the same time.
No bank in Canada can offer you that in a single contract.
To see how this structure would look applied to your real situation in Canada, the first step is to complete the Financial Efficiency Assessment for Canada. It is free and shows you exactly how much capital you could be building today:
Complete My Financial Efficiency Assessment
The Next Step
Becoming your own banker (infinite banking) in Canada does not mean choosing between having money available today or protecting your family tomorrow. It means having both at the same time, within the same contract, with guarantees protected by Canadian legislation.
If you are ready to speak with a specialist and design your structure in the Canadian financial context, book your strategy session here:
This content is educational. Consult a qualified professional in Canada before making financial decisions based on your personal situation.