The Secret Recipe of Infinite Banking in Canada: Base Premium and Deposit Options Explained
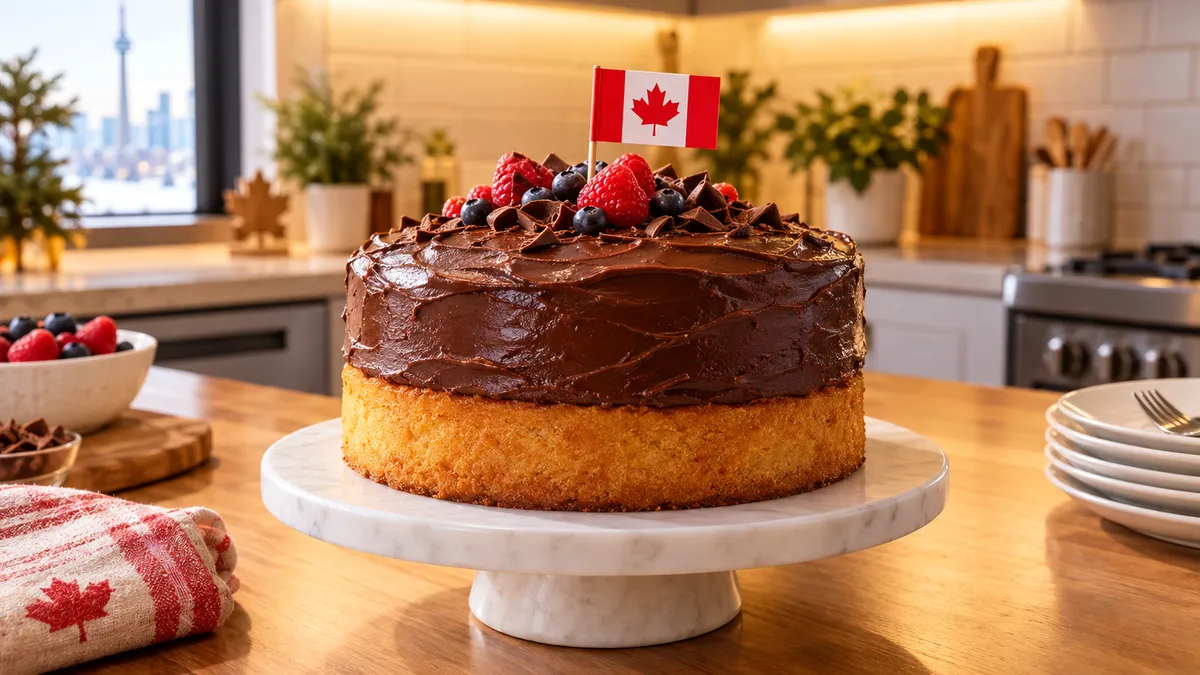
To bake a delicious cake you need two key ingredients: flour to give it firmness and structure, and chocolate to give it flavor, body, and richness.
If you use only flour, the cake turns out hard and tasteless. If you use only chocolate without flour, it melts in the oven and is useless.
The secret is in the right proportion.
When we design a participating whole life policy for the Personal Banking System in Canada, we do exactly the same thing. We blend two types of money contributions in the right proportion so the system produces maximum available cash without losing the tax protection that makes it so powerful.
That blend has a name: Base Premium and Deposit Options.
Ingredient 1: The Base Premium (The Flour)
The Base Premium is the mandatory cost of the traditional whole life insurance. It is the backbone of the contract.
The Base Premium serves two fundamental functions:
It builds the permanent legal structure. It guarantees the policy lasts the Insured's entire lifetime regardless of what happens in the economy, your future health, or the financial markets.
It protects the tax shield under Canadian rules. The Base Premium establishes the minimum floor that defines how many additional contributions the policy can receive without crossing the MTAR limit (Maximum Tax Actuarial Reserve, also known as Maximum Tax Accrual Rules). These rules define how much money you can deposit and grow tax-free inside a permanent life insurance policy in Canada, under Sections 148 and 306 of the Income Tax Act.
Without a solid Base Premium, there is no tax shield. And without a tax shield, the system stops being a Personal Banking System and becomes an ordinary taxable instrument.
Ingredient 2: Deposit Options (The Chocolate)
Deposit Options are what make the system extraordinarily efficient for personal banking. In Canada, this component is called Deposit Options inside the contracts of Canadian mutual life insurance companies. It is the same concept known as PUA (Paid-Up Additions) in the US market, with the same purpose and logic, but with the proper name for the Canadian market.
Every dollar you deposit as a Deposit Option immediately purchases additional fully paid-up insurance inside your policy. That additional paid-up insurance converts almost instantly into available cash value for you from the first year.
In simple terms: Deposit Options are the cash value growth accelerator. They are what makes the money you contribute available quickly instead of getting trapped in years of initial charges, as happens with poorly designed policies or Universal Life policies.
Deposit Options are not mandatory. You can adjust your contributions according to your cash flow at different moments in your life. That flexibility is one of the most practical advantages of the Personal Banking System in Canada.
The Golden Rule: The Right Proportion
Here is the critical point that many inexperienced advisors ignore, and that can cost a family years of lost tax benefits.
If the Base Premium is too small relative to the Deposit Option contributions, the CRA (Canada Revenue Agency) classifies the policy as exceeding the MTAR limit. When that happens, the policy stops being an exempt contract and loses the tax advantages protected by Sections 148 and 306 of the Canadian Income Tax Act.
In other words, if the chocolate is disproportionately more than the flour, the cake collapses in the oven.
Some advisors offer extreme designs that show a lot of available cash in the short term. Those designs may look attractive in a presentation, but if they do not respect the correct proportion between Base Premium and Deposit Options, the system loses its tax efficiency and stops functioning as a Personal Banking System.
The golden rule is always to maintain a solid Base Premium that protects the tax shield, and on top of that base, maximize Deposit Option contributions within the allowed limit. That way you get the maximum available cash without putting any tax advantage at risk.
How Do You Know If Your Policy Has the Right Mix?
This is a question everyone with a whole life policy in Canada should ask their advisor.
If your policy was designed primarily to show a lot of available cash quickly without clearly explaining the Base Premium, Deposit Options, and the MTAR limit, it is worth reviewing the structure with a specialist.
If you are considering opening a policy and want to make sure the design is correct from day one, the first step is to understand your current financial situation in Canada and calculate the ideal mix for your profile.
You can start with the Financial Efficiency Assessment for Canada. It is free and helps you understand how much capital you could be optimizing today:
Complete My Financial Efficiency Assessment
The Right Mix Is the Foundation of Everything
A well-made cake is not improvised. It follows a proven recipe, with exact proportions, and is baked with care.
Your Personal Banking System is not improvised either. It is designed with precision, with the correct mix of Base Premium and Deposit Options, respecting Canadian tax limits, with the clear objective that every dollar you contribute works to its maximum for you today and for your family tomorrow.
Becoming your own banker (infinite banking) in Canada starts with having the right recipe. And the right recipe can only be designed with a specialist who deeply understands the Canadian financial and tax context.
If you are ready to take that step, book your strategy session here:
This content is educational. Consult a qualified professional in Canada before making financial decisions based on your personal situation.