The 6 Mistakes That Destroy Your Personal Banking System in Canada (And How to Avoid Them)
Learning to pilot an airplane is an extraordinary experience.
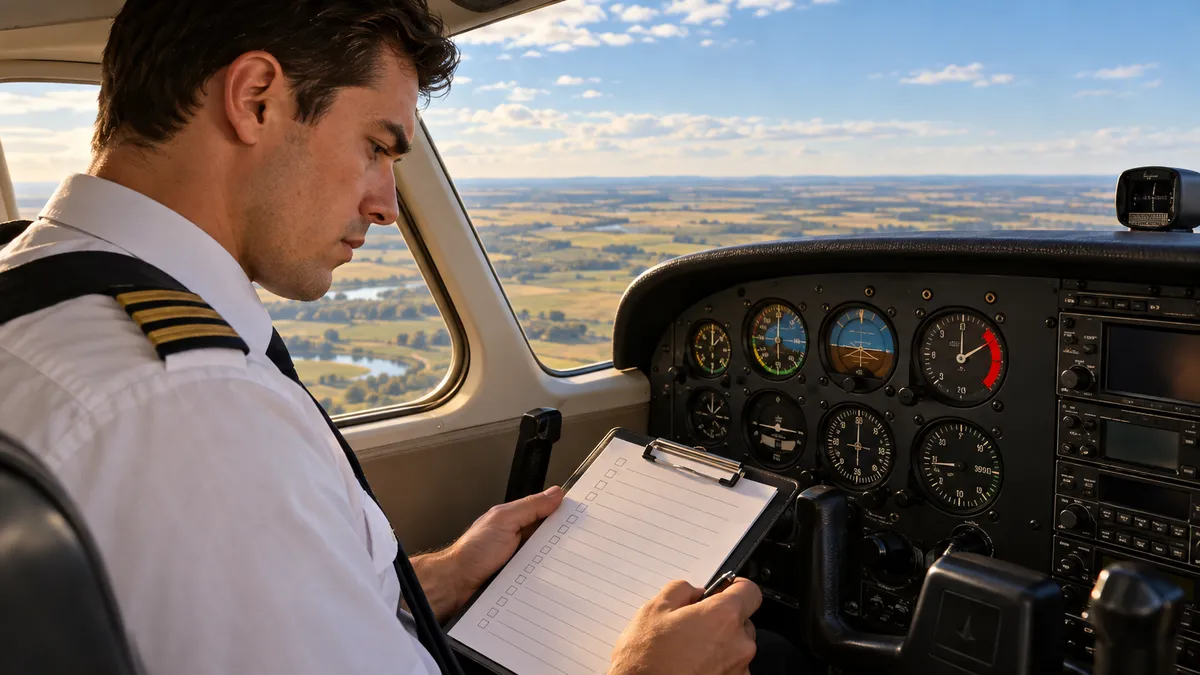
The airplane is a powerful, fast machine capable of taking you to places that would take days to reach on the ground. But there is something every pilot learns from day one: before taking off, there is a checklist that cannot be skipped. Not even once.
If the pilot does not check the fuel, ignores the instruments, or skips a step because they are in a hurry, the consequences can be devastating.
Your Personal Banking System for implementing the Infinite Banking Concept works exactly the same way.
It is a powerful tool. It can completely change the way your money works in Canada. But if you do not design and manage it carefully, the mistakes can cost you years of growth, lost tax benefits, and protections that disappear at the worst moment.
Here are the 6 most common mistakes. Know them before they cost you dearly.
Mistake 1: Only Paying the Minimum Required Premium
Many people open a participating whole life policy and only contribute the minimum required base premium.
The problem is that if you simultaneously accumulate large loans on the policy without a clear intention to repay them, the growth of your cash value stalls. The engine stays on, but without enough fuel to take off with force.
The correct strategy is to consistently capitalize the system, not just pay the minimum to keep it alive. A well-funded Personal Banking System grows exponentially. An underfunded one grows slowly and takes much longer to produce the capital you need.
Mistake 2: Abandoning the System in the Early Years
The first years of a participating whole life policy are like the first kilometers of takeoff. The airplane needs full power to gain altitude.
If you interrupt your contributions at that stage, it is like shutting off the engine just when you need it most. The system needs consistency at the start for compound interest to take flight.
This is one of the most costly and most frequent mistakes. Discipline in the early years defines the system's performance over the next twenty.
Mistake 3: Not Updating Your Beneficiaries
Life changes. You get married, divorced, have children, lose a loved one.
Many people in Canada open their policy and never revisit who their designated beneficiaries are. If you pass away with an outdated beneficiary, the money can go to the wrong hands, remain without a clear recipient, or pass into the probate process with a judge, generating costly delays and unnecessary losses for your family.
Updating your beneficiaries takes no more than a phone call to your Canadian mutual life insurance company. Not doing it can destroy in days what you built over years.
Mistake 4: Concealing Medical Information When Applying
When you apply for a whole life policy with a Canadian mutual life insurance company, they ask you about your health. Some people omit pre-existing conditions or downplay lifestyle habits thinking they will get a lower premium.
This is a serious mistake.
If the company discovers incorrect information, it can cancel the policy or refuse to pay the death benefit to your family. Transparency in the application is not optional. It is the legal foundation of the entire contract.
Mistake 5: Designing a Structure That Crosses the MTAR Limit
In Canada, participating whole life policies used for the Personal Banking System are regulated by the MTAR rules (Maximum Tax Actuarial Reserve, also known as Maximum Tax Accrual Rules). These rules define how much money you can deposit and grow tax-free inside a permanent life insurance policy in Canada.
This limit regulates the correct proportion between the base premium and additional deposits inside the policy. If someone designs a policy with excessive deposits without adequate base premium support, the policy can cross that limit and become a non-exempt contract under CRA (Canada Revenue Agency) rules.
When that happens, you lose the tax advantages protected by Sections 148 and 306 of the Canadian Income Tax Act. Essentially, the vehicle loses its fiscal engine and stops functioning as a Personal Banking System.
This mistake cannot be easily reversed. That is why the initial design is so critical.
If you want to review whether your current financial situation is well structured to implement this strategy in Canada, the first step is to complete the Financial Efficiency Assessment for Canada:
Complete My Financial Efficiency Assessment
Mistake 6: Trying to Do It Alone Without Certified Guidance
The Concept of becoming your own banker is not a product you simply buy. It is a strategy that is designed, structured, and managed with precision over time.
Applying these concepts without a certified professional in the Canadian context is the fastest way to make any of the five previous mistakes simultaneously. And in finance, mistakes that are not corrected in time multiply.
An advisor who does not understand the difference between the Canadian context and that of other countries, who does not know the MTAR, the ACB, or Sections 148 and 306 of the Canadian Income Tax Act, can design you a structure that looks good on paper but in practice delivers none of its promises.
Becoming your own banker (infinite banking) requires the same level of preparation as piloting an airplane. The pilot does not improvise. They follow the process, check the list, and take off with everything in order.
The Next Step
The 6 mistakes on this list are not theoretical. They are the real mistakes that happen when the Personal Banking System is implemented without the right guidance in Canada.
The good news is that all of them can be avoided when you have the right team and design from the beginning.
If you are ready to speak with a specialist in the Canadian financial context and make sure your strategy has no design flaws, book your session here:
This content is educational. Consult a qualified professional in Canada before making financial decisions based on your personal situation.