The 4 Roles Inside Your Policy in Canada: Who Does What in Your Infinite Banking System
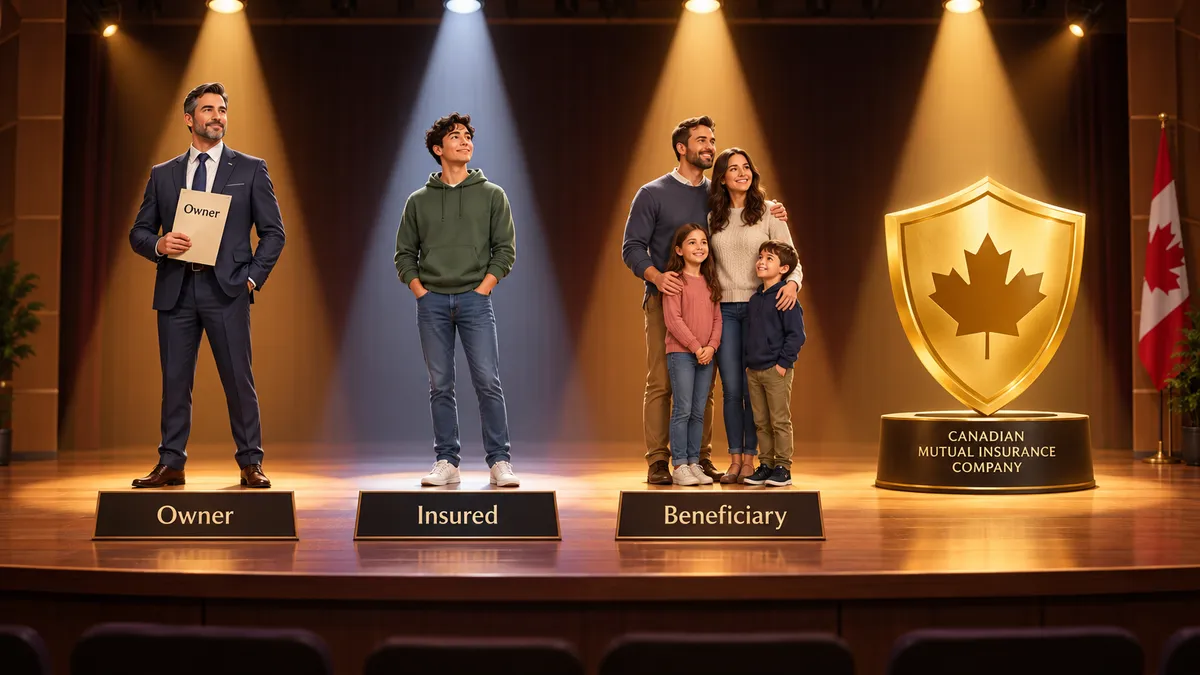
Imagine you go to the theater and the play begins.
On the stage there are four characters. Each one has a specific role, a defined script, and a responsibility that cannot be swapped with another's. If the actors get confused about their scripts, the play becomes chaos.
A participating whole life policy works exactly the same way. It has four main roles. When each one knows their role clearly, the system works with precision and the entire family benefits. When roles are confused or incorrectly assigned, the strategy loses efficiency, unexpected tax consequences can arise, and the benefit reaching the family may get trapped or reduced.
Understanding these four roles is one of the most important steps before designing your Personal Banking System in Canada.
Role 1: The Owner
The Owner is the director of the entire play. They are the person who holds all legal rights over the policy.
Only the Owner can:
- Take loans using the cash value as collateral.
- Change the designated beneficiaries.
- Modify the contract conditions.
- Transfer ownership of the policy to another person.
- Decide what to do with the dividends.
The Owner does not need to ask anyone's permission to make these decisions. That is exactly what it means to become your own banker (infinite banking): having complete control over your capital without depending on an external institution.
In Canada, the Owner can be an individual, a corporation, or even a trust, depending on the objectives of the family or business strategy.
Role 2: The Insured
The Insured is the person whose life is covered by the insurance contract.
Their age and health at the time of applying for the policy determine the cost of the base insurance. The younger the age and better the health, the lower the insurance cost and the more efficient the cash value growth.
Here is something very few people know in Canada: the Owner and the Insured do not have to be the same person.
A parent can be the Owner of a policy while insuring the life of their young child. A business can be the Owner of a policy on the life of a key partner. A person with health issues can be the Owner while insuring the life of their spouse, who enjoys better health.
This separation of roles opens strategic possibilities that most Latinos in Canada do not know about, and that can make an enormous difference in the efficiency of the entire structure.
Role 3: The Beneficiary
The Beneficiary is the person or entity chosen to receive the death benefit when the Insured passes away.
This money goes directly to the Beneficiary, income-tax-free, without going through the probate process in Canada. That means no delays, no legal costs, and no CRA (Canada Revenue Agency) intervention on that amount.
The Beneficiary can be:
- A spouse or partner.
- Children or grandchildren.
- A family trust.
- A corporation or business.
- A charitable organization.
The Owner can change the Beneficiary at any time, as long as the Beneficiary has not been designated as irrevocable. This flexibility is one of the most important advantages of the system, and another reason why keeping beneficiaries updated is not optional.
If beneficiaries are not updated, the money can go to the wrong people, remain without a clear recipient, or pass into the succession process and probate with a judge, generating costly delays and unnecessary losses for your family.
Role 4: The Insurer
The Insurer is the Canadian mutual life insurance company that issues the contract, holds the money reserves, guarantees the annual growth, and pays the death benefit when appropriate.
For the Personal Banking System in Canada, only Canadian mutual life insurance companies with over one hundred years of uninterrupted operating history are used.
Unlike shareholder-owned insurers, mutual companies have no external owners demanding profits. The only owners are the policyholders themselves, like you. When the company generates profits at year end, those profits return to policyholders as dividends deposited directly into your policy.
That means the company works for you, not for a group of unknown shareholders.
Why Coordinating the Four Roles Matters So Much
Incorrectly assigning roles can have real consequences in Canada.
If the structure is not designed with the correct separation of roles according to the family's objectives, opportunities for tax efficiency and protection that Canadian legislation allows are lost.
To analyze how to organize these four roles in your specific situation in Canada, the first step is to complete the Financial Efficiency Assessment for Canada:
Complete My Financial Efficiency Assessment
The Next Step
Coordinating these four roles within your family or business gives you financial flexibility that no traditional bank in Canada can offer you.
When the system is well designed from the start, each role fulfills its function with precision, capital grows efficiently, and the legacy reaches those it should without unnecessary delays or losses.
If you are ready to design your structure with a specialist in the Canadian financial context, book your session here:
This content is educational. Consult a qualified professional in Canada before making financial decisions based on your personal situation.