The 4 Factors to Qualify for Your Policy in Canada: Can You Open Your Infinite Banking System?
To obtain a commercial pilot's license in Canada, they do not hand the airplane to just anyone who applies.
They first carefully review your health history, your practice hours, your conduct record, and your real ability to operate the aircraft without putting anyone at risk. The process is rigorous because the consequences of doing it wrong are very high.
When you apply to open a participating whole life policy with a Canadian mutual life insurance company, something similar happens. It is not as complicated as getting a pilot's license, but there are four key personal factors the company evaluates before approving your application.
Knowing these four factors in advance allows you to prepare correctly, understand what to expect, and avoid surprises in the process.
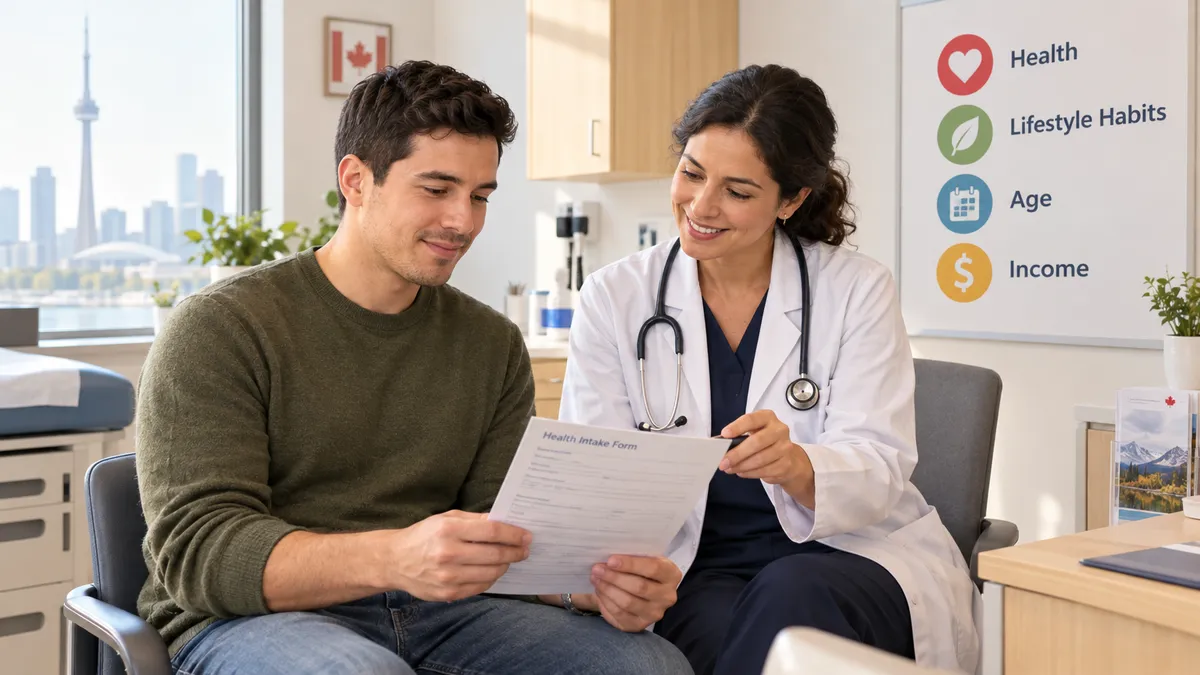
Factor 1: Your Current Health Status
The Canadian mutual life insurance company evaluates your medical history to determine the risk of insuring you.
The better your health at the time of applying, the lower the base insurance cost inside your policy. And a lower insurance cost means a greater proportion of every dollar you contribute converts into available cash value for you.
This has a very important practical implication: the sooner you apply, while you still have good health, the better the efficiency of your system from day one.
It is not about being perfect. Most people with manageable health conditions can qualify, sometimes with adjustments to the insurance cost or specific exclusions. The evaluation process is individual and confidential.
Factor 2: Your Lifestyle Habits
Smoking is one of the factors that most impacts insurance costs. Canadian mutual life insurance companies clearly distinguish between smoker and non-smoker policyholders, and the cost difference can be significant.
Practicing extreme high-risk sports, such as skydiving or professional mountaineering, can also increase costs or generate specific policy exclusions.
The good news is that if you quit smoking and maintain that change for a determined period, you may qualify as a non-smoker in a future review, which can considerably reduce your base insurance cost.
Factor 3: Your Current Age
Here is one of the most important truths about this system: the best time to start is today.
The younger you are when you open your policy, the lower the base insurance cost. A lower insurance cost means more efficiency in cash value growth from the start.
But that does not mean if you are 50 or 60 you cannot do it. In Canada you can obtain a whole life policy up to age 85. And if the insurance cost on your own life is very high due to age, there is a very powerful alternative: you can be the Owner of a policy on the life of your spouse, a child, or a grandchild.
That means you control the system, you decide when and how to use the money, and you are the beneficiary or designate whoever you choose. Age does not close the door. It just changes the design of the structure.
Factor 4: Your Declared Income
Canadian law requires that the amount of life insurance requested have a reasonable relationship to the applicant's income level and financial situation. This is called the insurable interest principle.
In simple terms, you cannot request a death benefit of five million dollars if your declared income does not justify that amount.
For Latinos in Canada with variable income, self-employment, or businesses that do not always have orderly tax returns, this is a factor worth preparing for in advance. Having your tax returns up to date and organized before applying considerably facilitates the process.
What If You Have a Serious Health Problem?
This is the question that most holds back people in the Latino community in Canada.
The answer is clear: a health problem does not eliminate you from the Personal Banking System.
If your health condition makes the insurance cost on your own life very high or your application is not approved, you can be the Owner of a policy on the life of another person with whom you have a recognized insurable interest. This includes your spouse, your children, your grandchildren, or a business partner.
You control the system. You access the capital. You designate the beneficiaries. The Insured is simply the person whose life is covered by the contract.
To analyze which is the best qualification strategy for your specific situation in Canada, the first step is to complete the Financial Efficiency Assessment for Canada:
Complete My Financial Efficiency Assessment
There Is No Age Too Late and No Amount Too Small
One of the ideas that most limits people is believing it is already too late to start, or that they do not have enough money for the system to be worthwhile.
Neither is true.
There is no age too late if you structure the system correctly. There is no amount too small to start, because the system can grow over time. And there is no health situation that closes all doors, because there is always the option of insuring someone else's life while you maintain control.
What does exist is the cost of not starting. Every year that passes without a system is one more year of money going to the bank and not to your family.
Becoming your own banker (infinite banking) in Canada starts by understanding where you are today and how to get from there to the system you want to build.
If you are ready to take that first step with a specialist in the Canadian financial context, book your strategy session here:
This content is educational. Eligibility criteria depend on each personal situation. Consult a qualified professional in Canada before making financial decisions.